This guide explains how AI voice agents for lending handle payment reminders, collections calls, and borrower support. You will learn how they work, where they fit across the loan lifecycle, which rules apply in the US, UK, EU, and Australia, and what they cost. It also compares vendor platforms with custom builds and shares a 90-day rollout plan.
Key Takeaways
AI voice agents for lending automate high-volume borrower calls, such as pre-due reminders, early-stage collections, promise-to-pay (PTP) capture, and balance or payoff questions. Humans handle disputes and hardship cases.
According to Grand View Research, the AI voice agents market is projected to grow from about $2.5 billion in 2025 to $35.2 billion by 2033, with BFSI as the leading end-use segment.
Under Regulation F, collectors are generally presumed to violate the call-frequency rule above 7 calls per debt in 7 days, and the FCC treats AI-generated voices as artificial under the TCPA.
Vendor platforms cost roughly $0.07–$0.30 per minute all-in. A custom build starts with a $3000 to $8000 proof of concept and a $10,000 to $50,000+ pilot-ready AI MVP.
A focused rollout can move from use-case selection to a measured pilot in about 90 days.
Lenders face a simple math problem. Borrower calls keep growing, but collections and servicing teams do not.
According to the New York Fed, US household debt stood at $18.8 trillion in Q2 2026, with 4.7% of it in some stage of delinquency. Every late account needs reminders, follow-ups and conversations.
Most of those calls follow the same pattern. Confirm identity, state the balance, offer a way to pay, log the outcome.
That is exactly the work AI voice agents now do. Grand View Research values the AI voice agents market at about $2.5 billion in 2025, rising to $35.2 billion by 2033. BFSI is the largest end-use segment.
Large players are already live. Auto lender Consumer Portfolio Services deployed Salient’s AI voice agents for servicing and collections in May 2025. ICE unveiled a beta AI voice agent for its MSP servicing platform in March 2026.
This guide covers what these agents do, where they fit, which rules apply, how they are built and what they cost.
What Are AI Voice Agents for Lending?
AI voice agents for lending are conversational AI systems that hold natural phone conversations with borrowers. They send payment reminders, run collections calls, and answer servicing questions. They connect to the lender’s loan management system (LMS), so they can read and update accounts in real time.
Each agent combines three layers: speech recognition, a large language model, and text-to-speech. Borrowers speak normally and do not need to use phone menus.
The agent also takes action. It can send a secure payment link, log a promise to pay, change a due date within policy, or transfer the call to a human with full context.
AI Voice Agent vs IVR vs Robocall
An AI voice agent holds a two-way conversation and completes tasks. An IVR routes callers through fixed menus. A robocall plays a one-way recorded message. Of the three, only the AI voice agent can resolve many borrower calls without a human.
Factor
Robocall
IVR
AI Voice Agent
Conversation
One-way message
Menu-driven
Two-way, natural speech
Understands free speech
No
Limited keywords
Yes
Takes actions
No
Basic (e.g., pay by keypad)
Pays, logs PTP, updates LMS, transfers
Personalization
Name merge only
Account lookup
Live balance, history, tone
Handles interruptions
No
No
Yes
Best use
Mass notices
Call routing
Reminders, collections, servicing
AI Voice Agent vs Human Collector: Where Each Fits
AI voice agents work best for high-volume, rule-based calls. Human collectors work best for disputes, hardship, vulnerable borrowers, and negotiations outside pre-approved limits. A hybrid model, where AI handles routine calls and humans handle the rest, is the most common setup.
Task
AI Voice Agent
Human Collector
Pre-due and due-date reminders
Best fit
Not cost-effective
Early-stage collections (1–30 past due, DPD )
Best fit
Backup for escalations
Balance, payoff and due-date questions
Best fit
Complex exceptions
Pre-approved payment plans
Good fit
Custom plans
Disputes and legal threats
Detect and transfer
Owns the case
Hardship and vulnerability
Detect and transfer
Owns the case
Why Lenders Are Adopting AI Voice Agents Now
Lenders are adopting AI voice agents because call volumes are rising faster than headcount, labor dominates contact center costs, and borrowers expect answers outside office hours. AI voice agents address all three at once.
1. Rising Delinquency and Servicing Volumes
Delinquency is not falling fast. Transitions into serious mortgage delinquency reached 1.52% in Q2 2026, up from 1.29% a year earlier.
Each extra late account adds reminder calls, follow-ups and inbound questions. Hiring more collectors scales linearly. AI voice agents does not.
2. Contact Center Costs and Agent Attrition
Labor can represent up to 95% of contact center costs, according to Gartner.
Gartner also projected that conversational AI would reduce contact center agent labor costs by $80 billion in 2026.
Collections roles are repetitive and stressful. That drives turnover, retraining and inconsistent call quality.
3. Borrowers Expect 24/7 Support
Borrowers check balances and payment options in the evening and on weekends. Most servicing teams work business hours.
A voice agent answers instantly, at any hour. ICE says its servicing voice agent can manage thousands of simultaneous interactions.
For most lenders, voice AI is one part of a wider fintech software development roadmap that also covers the LMS, payments and borrower apps.
How AI Voice Agents Work in a Lending Workflow
An AI voice agent turns the borrower’s speech into text. It then uses a language model and business rules to decide the next step, reads or updates data in the loan system, and replies in a synthesized voice. A well-built system aims to complete this loop in about one second.
Core Components
A lending-grade voice agent has seven core components. The rules engine is what separates it from a generic voice bot.
Component
What It Does
Lending Requirement
Telephony / Contact Center
Places and receives calls
Caller ID, consent-aware dialing, call recording where permitted
Speech-to-text (STT)
Turns speech into text
Accuracy on names, amounts, dates, accents
Language Model (LLM)
Understands intent, writes replies
No guessing on balances or terms
Rules and Compliance Engine
Enforces policy before each action
Call caps, time windows, disclosures, consent
Text-to-speech (TTS)
Speaks the reply
Clear, calm voice; multilingual
Integration Layer
Connects to LMS, customer relationship management (CRM), payment
Real-time reads and writes, audit logs
Analytics and QA
Scores calls and outcomes
Compliance monitoring on recorded calls
A Payment Reminder Call, Step by Step
A compliant reminder call follows seven steps, and the first one happens before the phone rings.
1. Eligibility Check: The system confirms consent, local time, call caps and do-not-call status.
2. Dial and Disclose: The agent introduces the lender and, where required, states that it is an AI assistant.
3. Right-party Verification: The agent confirms identity before mentioning any account details.
4. Reminder: It states the amount and due date, pulled live from the LMS.
5. Borrower Response: Pay now (secure link or keypad), promise to pay, or request help.
6. Escalate if Needed: Disputes, hardship or a request for a person go to a human.
7. Log and Follow Up: The outcome is written to the LMS and CRM, and the next touch is scheduled.
How Human Handoff Works
Human handoff transfers the call to a live agent along with the transcript, account details, and the reason for transfer. The borrower does not need to repeat anything. ICE built its servicing voice agent to pass loan details and context on every transfer (ICE, March 2026).
Common handoff triggers include:
The borrower disputes the debt or the amount.
The borrower mentions job loss, illness, bereavement or financial hardship.
The borrower asks for a person.
The borrower mentions an attorney, bankruptcy or legal action.
The agent’s confidence in its understanding drops below a set threshold.
A requested payment plan falls outside pre-approved limits.
AI Voice Agent Use Cases Across the Loan Lifecycle
AI voice agents cover seven core lending use cases: pre-due reminders, early-stage collections, late-stage collections, PTP follow-up, hardship conversations, inbound borrower support, and onboarding follow-up. Reminders and inbound questions are the usual starting points because they are high-volume and low-risk.
Stage
Use Case
Automation Level
Key KPI
Before due date
Pre-due reminders, autopay enrollment
High
On-time payment rate
1–30 DPD
Early-stage collections
High
Cure rate
31+ DPD
Late-stage collections, settlements
Medium
Recovery rate
After a promise
PTP reminders and follow-up
High
PTP kept rate
Any stage
Hardship and payment plans
Low (assist)
Plan completion rate
Any time
Inbound borrower support
High
Containment rate
Origination
Document and onboarding follow-up
High
Time to funding
Pre-Due Payment Reminders
Pre-due reminders are the safest place to start. The borrower has not missed anything yet, so the call is friendly and low-risk.
The agent confirms the amount and date, offers to take the payment early, and suggests autopay. Preventing a missed payment costs far less than collecting one.
Early-Stage Collections (1–30 DPD )
Many early-stage accounts cure with a single well-timed nudge. Volume is high and conversations are similar.
The agent explains the missed payment, offers a pay-now option and captures a PTP if needed. It runs within the call cadence your compliance team sets.
Late-Stage Collections and Settlements
Late-stage calls are harder and need tighter guardrails. The agent can present pre-approved settlement or installment options and confirm the borrower’s choice.
Anything outside those limits goes to a human negotiator. Third-party collectors must also deliver the required collection disclosure on every call.
Promise-to-Pay Capture and Follow-Up
PTP are only useful if they are kept. The agent records the amount and date in the LMS, sends a reminder before the date and checks in if the payment does not arrive.
This closes a common gap where promises are logged but never followed up.
Hardship and Payment Plan Conversations
Hardship calls need human judgment. The agent’s job is to recognize hardship signals, collect basic information and route the call to a specialist.
It can offer standard plans where policy allows. It should never make final decisions for vulnerable borrowers on its own.
Inbound Borrower Support
Inbound calls are often the fastest win. Balance checks, payoff quotes, due-date changes, autopay setup and insurance updates are all routine.
CPS uses its voice agents for payment collection, due-date adjustments, payoff management and insurance verification.
Onboarding and Document Follow-Up
Voice agents also help before the loan is funded. They chase missing documents, confirm application details and schedule calls with loan officers.
Lendflow runs more than 30 AI agents across the lending lifecycle and says its voice AI saves over 500 hours of phone time every week.
AI Voice Agent for Debt Collection: What It Can and Can’t Do
An AI voice agent for debt collection can verify identity, give required disclosures, send reminders, take payments, and capturePTP. It should not handle disputes, legal threats, bankruptcy cases, or negotiations outside pre-approved limits.
Task
Automate
AI Assists, Human Decides
Human Only
Identity verification
✓
X
X
Required disclosures
✓
X
X
Reminders and balance updates
✓
X
X
Payment capture (PCI-safe flow)
✓
X
X
Promise-to-pay logging
✓
X
X
Pre-approved payment plans
✓
X
X
Hardship assessment
X
✓
X
Custom settlements
X
✓
X
Disputes and validation requests
X
X
✓
Attorney, bankruptcy or legal threats
X
X
✓
Key Features to Look For in a Lending Voice Agent
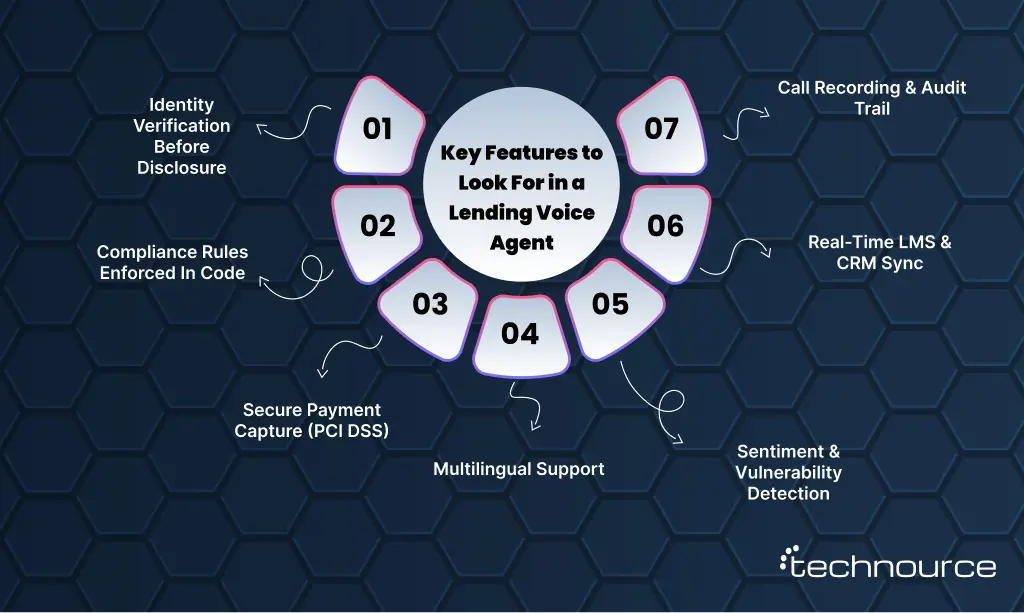
The must-have features are identity verification before disclosure, compliance rules enforced in code, PCI-compliant payment capture, multilingual support, sentiment detection, real-time LMS sync, and a full audit trail. A gap in any one of these creates regulatory or customer risk.
Identity Verification Before Disclosure
The agent must confirm it is speaking to the borrower before it mentions any account detail. Sharing a debt with the wrong person can break the FDCPA’s third-party disclosure rules. If someone else answers, the agent leaves only a neutral callback message.
Compliance Rules Enforced in Code
Call windows, frequency caps, consent and disclosures should be hard checks in the rules engine. They should not depend on the language model “remembering” a prompt.
If a rule fails, the call does not happen.
Technource’s Recommendation: Build call limits, calling hours, and consent checks as fixed rules in the system. Do not rely on the language model to remember them, so no call breaks a rule.
Secure Payment Capture (PCI DSS)
Card numbers should never pass through the language model or appear in transcripts. Use keypad entry with masking, or send a secure payment link by SMS.
Multilingual Support
Many lenders serve borrowers who speak more than one language. Modern agents can handle several languages and regional accents. Venture capital firm a16z notes that Salient’s agents can handle callers in multiple languages (a16z).
Sentiment and Vulnerability Detection
The agent should flag distress, confusion or mentions of illness and job loss. These signals trigger a softer script or an immediate human transfer.
Real-Time LMS and CRM Sync
Stale data causes wrong balances and angry borrowers. The agent must read live data before speaking and write every outcome back after the call.
Call Recording and Audit Trail
Where legally permitted and appropriate, record and transcribe calls for quality assurance and compliance monitoring. Apply the required consent or notification procedures, restrict access, and set retention periods according to applicable privacy and regulatory requirements.
Benefits of AI Voice Agents for Lenders
The main benefits are wider contact coverage, lower cost per contact, faster borrower service, more collector time for complex cases, and consistent compliance. Results depend on the use case you choose and how well the agent is integrated.
Benefit
What Changes
Evidence
Higher contact coverage
Every account gets timely outreach
ICE: thousands of simultaneous interactions
Lower cost per contact
Routine calls move from salaried agents to per-minute AI
Vendor pricing: ~$0.07 to ~$0.30 per minute
Faster resolution
Structured calls, no hold queues
Salient: handle times cut by 60%
Team capacity
Hours freed for complex work
Lendflow: 500+ phone hours saved weekly
Consistent compliance
Same disclosures and limits on every call
Rules checked before every call
Higher Contact Coverage
Human teams prioritize the biggest balances. Smaller accounts often get no call until they roll into a later bucket.
A voice agent can reach every eligible account on schedule.
Lower Cost per Contact
Routine reminder calls are cheap for AI and expensive for people. Shifting them frees budget for specialist collectors.
Consistent Compliance
A voice agent delivers the same approved disclosure every time. It cannot skip a script line on a busy day.
Better Borrower Experience
Borrowers get instant answers, at any hour, without hold queues. Salient reports that its platform helped lenders cut handle times by 60%.
Collectors Focus on Complex Cases
When AI handles routine volume, experienced collectors spend their time on hardship, disputes and high-balance negotiations.
Compliance Rules for AI Voice Agents in Lending
AI voice agents must follow the same collection and consumer protection rules as human agents. They also face AI-specific rules. In the US, the FCC treats AI-generated voices as artificial under the TCPA. In the EU, the AI Act requires AI disclosure from 2 August 2026.
Region
Key Rules
What It Means for a Voice Agent
United States
FDCPA, CFPB Regulation F, TCPA
Call caps, calling hours, disclosures, consent rules for AI-voice calls
United Kingdom
FCA Consumer Duty, CONC
Good outcomes, easy access to humans, vulnerable customer care
European Union
AI Act Article 50, GDPR
Tell callers they are talking to AI; lawful data handling
Australia
ASIC and ACCC Debt Collection Guideline
No more than 3 contacts per week or 10 per month
United States: FDCPA, Regulation F and TCPA
US collection calls are governed by three overlapping rule sets. Each one applies to AI calls exactly as it does to human calls.
Call Frequency (Regulation F): Under CFPB Regulation F, a debt collector is generally presumed to violate the call-frequency rule if it places more than seven calls about a particular debt within seven consecutive days, or calls again within seven days after a telephone conversation about that debt. Exceptions may apply, so the dialing engine should enforce the rule alongside applicable federal and state requirements.
Calling Hours (FDCPA): Calls are generally limited to 8 a.m.–9 p.m. in the borrower’s local time.
AI Voices (TCPA): The FCC confirmed on 8 February 2024 that AI-generated voices qualify as artificial or prerecorded voices under the TCPA. Depending on the call type and recipient, these calls may require prior express consent or prior express written consent. Lenders should verify applicable consent and identification requirements before deploying outbound campaigns.
Disclosures: Third-party collectors must state that the call is an attempt to collect a debt.
Scope: The FDCPA mainly covers third-party collectors, but many first-party lenders adopt the same standards, and some state laws extend them to creditors.
United Kingdom: FCA Consumer Duty
The FCA’s Consumer Duty has applied since 31 July 2023 for open products. It requires firms to deliver good outcomes for retail customers.
For voice agents, that means easy access to a human, clear explanations and extra care for customers in vulnerable circumstances. An agent that traps borrowers in loops would fail this test.
European Union: AI Act and GDPR
Article 50 of the EU AI Act applies from 2 August 2026. Voice agents must tell people they are interacting with AI.
Article 50 breaches can draw fines of up to €15 million or 3% of global turnover.
GDPR also applies to call recordings, transcripts and retention. AI used for credit scoring falls under separate high-risk rules, now due from December 2027.
Australia: ASIC and ACCC Debt Collection Guideline
ASIC guidance limits collection contact to a maximum of three phone calls or letters per week, or ten per month.
No contact is allowed on national public holidays. Privacy rules also bar discussing the debt with anyone else.
Integrations and Tech Stack for Lending Voice Agents
A lending voice agent needs integrations with the loan management system, CRM, payment gateway, telephony or contact center platform, and consent and identity records. AI Integration depth decides whether the agent can actually resolve calls.
Systems to Connect
A lending voice agent needs to connect to the loan management system (LMS), CRM, payment gateway, telephony or contact center platform, and consent and identity records. How deep these links go decides how many calls the agent can resolve on its own. The agent should read data before it speaks and write data after it acts.
System
Agent Reads
Agent Writes
Loan management system (LMS)
Balance, due date, DPD, payment history
PTP, due-date changes, call outcome
Loan origination system (LOS)
Application status, missing documents
Document received, next step
CRM
Contact preferences, past interactions
Call notes, sentiment, next action
Payment gateway
Payment status
Payment confirmation, receipt
Consent and DNC records
Consent status, opt-outs
New opt-outs, revocations
Telephony / CCaaS
Call events, transfers
Recordings, routing to human queues
Recommended Tech Stack
Most production builds combine proven voice infrastructure with a custom rules and integration layer. Training models from scratch is rarely needed. The tools below are common examples, not endorsements, and the right choice depends on your region, languages, and data rules.
Layer
Common Options
Telephony
Twilio, Azure Communication Services, Amazon Connect, Genesys
Speech-to-text
Deepgram, Azure Speech, Google Speech-to-Text, Whisper
Language model
GPT, Claude or Gemini models, or fine-tuned open models
Text-to-speech
ElevenLabs, Azure Neural TTS, Cartesia
Voice orchestration
LiveKit, Pipecat, or managed platforms such as Vapi or Retell
Rules and compliance
Custom policy engine with deterministic checks
Data and logs
PostgreSQL, Redis, encrypted object storage
Our AI agent development team picks components per project based on latency, language coverage, data residency and cost.
Latency, Accuracy and Scale Targets
A lending voice agent should respond in about one second, transcribe amounts and dates accurately, and scale to peak call volumes without dropping calls. Slow replies make borrowers talk over the agent and hang up.
Response time: about 1 second from end of speech to start of reply.
Accuracy: test names, amounts, dates and account numbers on real call audio.
Concurrency: size for month-end and due-date peaks, not average volume.
Uptime: fail over to a human queue if any component fails.
Build vs Buy: Vendor Platform or Custom Voice Agent?
Buy a vendor platform when you need a standard use case live quickly on a common stack. Build a custom voice agent when you need deep LMS integration, your own compliance logic, full data control or a capability you plan to offer inside your own product.
Factor
Vendor Platform
Custom Build
Time to first call
Days to weeks
3–4 weeks (PoC)
Pricing model
Per minute plus platform fees
Build cost plus raw usage costs
LMS integration
Prebuilt for common systems
Any system, including legacy
Compliance logic
Vendor’s rules and settings
Your rules, your audit trail
Data control
Shared with vendor
Your cloud, your retention
Differentiation
Same as competitors
Unique borrower experience
Long-term cost at scale
Rises with every minute
Lower per-minute cost at high volume
When a Vendor Platform Makes Sense
A vendor platform works best when you need a standard use case live quickly on a common setup.
You need one standard use case live in weeks.
Your LMS is a common platform the vendor already supports.
Call volume is modest, so per-minute pricing stays affordable.
You have no plan to offer voice features inside your own product.
When a Custom Build Makes Sense
A custom build works best when you need deep system integration, your own compliance rules, or full control of your data.
Your LMS is custom or legacy, with no off-the-shelf connector.
You operate across several regions with different rules.
Data residency or retention rules require full control.
Your call volume makes per-minute fees a large, growing cost.
Many lenders choose a middle path. They build a custom agent on proven voice infrastructure, connected to their wider AI-powered workflow automation across servicing and collections.
How Much Does an AI Voice Agent for Lending Cost?
Vendor voice AI platforms cost roughly $0.07-$0.30 per minute all-in. A custom build typically starts at $3000 – $8000 for a proof of concept and $10000 – $50000+ for a pilot-ready AI MVP, with production costs depending on integrations and compliance scope.
Vendor Platform Pricing
Per-minute pricing bundles several layers: telephony, speech-to-text, the language model, text-to-speech and a platform fee.
Published 2026 rates for developer platforms such as Vapi, Retell and Bland work out to about 0.07-0.30 per minute once all layers are included.
Worked Example: 50,000 call minutes a month × 0.07-0.30 = roughly $3500-$15,000 per month.
Enterprise lending platforms usually quote custom pricing that bundles compliance features and integrations.
Custom Build Cost by Scope
Custom builds are best priced in stages. Each stage proves value before the next investment.
Stage
Scope
Typical Cost
Timeline
Proof of concept
One call flow, test data, basic voice loop
$3000- $8000
3–4 weeks
Pilot-ready AI MVP
One use case, LMS integration, compliance rules, handoff
$10,000 – $50,000
8–12 weeks
Production platform
Several use cases, regions, analytics, QA at scale
Scoped per project
4–6 months
Ongoing Running Costs
A custom agent still pays for usage. The difference is that you pay raw component prices instead of a vendor margin.
Speech, model and voice API usage per minute.
Cloud hosting and telephony numbers.
Monitoring, QA reviews and compliance audits.
Prompt, rule and model updates as policies change.
What Drives the Cost
The more use cases, systems, and regions you include, the higher the cost, so many teams start with one use case and expand later.
Number of use cases (reminders only vs full collections and servicing).
Integration complexity, especially legacy or custom LMS platforms.
Languages and regions, each with its own scripts and rules.
Payment handling, which adds PCI scope.
Analytics depth, from basic call logs to full QA scoring.
How to Implement an AI Voice Agent: A 90-Day Rollout Plan
A focused rollout takes about 90 days: two weeks to choose the use case and map rules, six weeks to build and integrate, and four weeks to pilot on a small portfolio segment. Scaling starts only after the pilot beats a human control group.
Phase
Weeks
Output
Use case and rules
1–2
Signed-off scripts, rules, handoff triggers
Build and integrate
3–8
Working agent connected to LMS, CRM, payments
Pilot
9–12
KPI results vs a human-only control group
Scale
12+
More segments, use cases and languages
Step 1: Pick One High-Volume Use Case
Start with pre-due reminders or inbound balance questions. Both are high-volume, low-risk and easy to measure.
Technource’s Recommendation: Start with pre-due reminders or inbound balance questions.
These use cases involve high call volumes and relatively low-risk interactions.
Step 2: Map Compliance and Escalation Rules
Work with your compliance team to approve scripts, disclosures, call caps and handoff triggers. Turn each rule into a testable check.
Step 3: Build and Integrate
Connect the agent to your LMS, CRM, payment gateway and consent records. Test on real call audio, not only clean samples.
Run the agent on a small, defined slice of accounts. Keep a matched human-only group for comparison.
Review a sample of calls every day during the first two weeks.
Step 5: Measure, Tune and Scale
Compare KPIs against the control group. Fix weak call flows, then add segments, languages and use cases one at a time.
KPIs to Measure AI Voice Agent Performance
Track right-party contact rate, PTP kept rate, cure rate, roll rate, containment rate, cost per contact and complaint rate. Compare each against a human-only control group, not against last year.
KPI
What It Measures
Why It Matters
Right-party contact rate
Calls that reach the actual borrower
No contact, no resolution
PTP kept rate
Promises that turn into payments
Shows real collection impact
Cure rate
Accounts brought current
Core early-stage outcome
Roll rate
Accounts moving to a worse bucket
Early warning on strategy
Containment rate
Calls resolved without a human
Drives cost savings
Cost per contact
Total cost per completed call
Proves ROI
Complaint rate
Complaints per 1,000 calls
Guards compliance and brand
Challenges and Risks of AI Voice Agents in Lending
The biggest risks are wrong account information, slow or unnatural replies, missed hardship cues, consent and disclosure gaps, voice fraud and borrower distrust. Each one is managed through system design, not model choice alone.
Wrong or Made-Up Account Information
Risk: The model states an incorrect balance or invents a policy.
Fix: Pull every number from the LMS in real time. Block the model from stating figures it did not retrieve.
Latency and Unnatural Conversations
Risk: Long pauses make borrowers talk over the agent or hang up.
Fix: Use streaming speech components, keep prompts short and test on real phone lines.
Missed Hardship Cues
Risk: The agent keeps pushing for payment when the borrower is in crisis.
Fix: Train hardship detection on real phrases and make the default action a human transfer.
Consent and Disclosure Gaps
Risk: The agent calls without valid consent or skips a disclosure.
Fix:Run consent, time and cap checks before dialing. Play required disclosures as fixed audio or locked text.
Voice Fraud and Deepfake Risk
Risk: Fraudsters use cloned voices to impersonate borrowers.
Fix: Never rely on voice alone. Use knowledge checks, one-time codes or app-based verification for sensitive actions.
Borrower Distrust of AI
Risk: Some borrowers may hang up when they learn they are speaking with an AI.
Fix: Be upfront, keep calls short, and always offer a human. Clear disclosure builds trust faster than trying to sound human.
Real-World Examples of Voice AI in Lending
Lenders and servicers including Consumer Portfolio Services, Lendflow and ICE Mortgage Technology already run AI voice agents for collections, servicing and borrower support. Their results show where the technology works today.
Lendflow
Lendflow runs more than 30 context-aware AI agents across application, servicing and renewal.
Its voice AI saves over 500 hours of phone time every week.
ICE Mortgage Technology
In March 2026, ICE unveiled a beta AI voice agent built into its MSP servicing platform.
It handles thousands of simultaneous calls and passes loan details and context to human agents on transfer.
How Technource Builds AI Voice Agents for Lenders
Technource is a product engineering company that builds AI-powered platforms and workflow automation for fintech and other regulated industries. We build voice agents as part of the lending product, not as an add-on.
Our Product Engineering Approach
Discovery: map call types, volumes, rules and systems before writing code.
Compliance-first architecture: rules, consent and disclosures enforced outside the model.
Deep integration: direct connections to your LMS, CRM, payments and identity tools.
Staged delivery:proof of concept, pilot, then production, with KPIs at each gate.
Ongoing optimization: call reviews, rule updates and model tuning after launch.
Case Study: VoiceMate AI – Multilingual AI Voice Call Assistant
Technource built a voice agent for an enterprise client in Greece that operates inside Microsoft Teams. It uses Azure Communication Services and ElevenLabs speech, with intent detection, smart routing, and instant human transfer. Recordings delete after 15 days for GDPR.
70% less reliance on human agents
80% faster responses to customer inquiries
Why it matters for lending: the same intent detection, handoff, and retention controls apply to borrower support lines. Read the VoiceMate AI case study.
Want Results Like These for Your Lending Operation?
Voice AI in lending is moving toward faster speech models, omnichannel collections, clearer AI disclosure rules, and smarter contact timing. Lenders that build flexible systems now will find it easier to adapt.
Faster Speech-to-Speech Models
Newer models process speech directly instead of passing text between three separate systems. That cuts response time and makes conversations feel more natural.
Omnichannel Collections
Voice will work alongside SMS, WhatsApp, email and in-app messages, with one shared record of every touch. A borrower can start on a call and finish with a payment link.
Stricter AI Disclosure Rules
EU AI Act transparency rules took effect in August 2026. More regulators are expected to require clear AI disclosure on calls.
Predictive Contact Strategy
Models will choose the best time, channel and message for each borrower. ICE already uses AI-based call prediction to anticipate why borrowers call.
Workflow Automation Beyond the Call
The call is only part of the job. Agents will increasingly complete the back-office tasks that follow, such as updating records, sending documents and opening hardship cases.
Conclusion
AI voice agents for lending are now practical, proven and growing fast. They handle reminders, early collections and routine servicing at a scale human teams cannot match.
Success depends on three things: compliance enforced in code, deep integration with your loan systems and a clear handoff to humans for hard cases.
Start with one high-volume use case, pilot it against a control group and scale what works.
Planning to implement voice AI for payment reminders, collections, or borrower support? Technource offers custom AI development services to help you design and build tailored AI voice solutions that align with your lending workflows, compliance requirements, and business goals.
Ready to Build a Compliant AI Voice Agent for Lending?
An AI voice agent for debt collection is a conversational AI system that calls borrowers, verifies identity, gives required disclosures, and reminds them of missed payments. It can take payments and log promises to pay through the loan system. It usually starts with early-stage accounts, 1-30 days past due. Disputes, hardship, and legal issues go to human collectors.
Yes, when they follow the same rules as human collectors. In the US, the FCC ruled on 8 February 2024 that AI-generated voices are artificial under the TCPA, so consent requirements may apply depending on the call type and recipient . Regulation F also presumes a violation above 7 calls about one debt in 7 consecutive days (FCC; CFPB). Confirm your setup with legal counsel.
In many markets, yes. From 2 August 2026, Article 50 of the EU AI Act requires that people be told when they interact with AI. Fines can reach €15 million or 3% of global turnover. In the US, artificial-voice calls must identify the caller, and some states are adding their own AI disclosure rules.
Vendor platforms cost about $0.07-$0.30 per minute all-in, covering telephony, speech recognition, the language model, and voice synthesis (Morph, July 2026; Dasha, 2026). At 50,000 call minutes a month, that is about $3,500 to $15,000. Enterprise lending platforms usually quote custom pricing that includes compliance features, integrations, and support.
A custom build usually starts with a proof of concept at $3,000 to $8,000 over 3-4 weeks. A pilot-ready AI MVP for one use case, such as pre-due reminders, costs $10,000 to $50,000+ over 8-12 weeks. Production platforms are scoped per project. These are Technource estimates.
An IVR routes callers through fixed menus and keypad or keyword inputs. An AI voice agent understands free speech, handles interruptions, pulls live account data, and completes tasks such as taking a payment or logging a promise to pay. IVRs suit simple routing, while AI voice agents such as ICE’s can manage thousands of simultaneous calls (ICE, March 2026).
Yes, within limits the lender sets. Payment plans usually come up with late-stage accounts, 31 or more days past due. The agent can offer pre-approved options, such as a standard installment plan or a settlement range, and record the borrower’s choice in the loan system. Hardship cases, disputes, and custom settlements go to trained staff.
A focused deployment for one use case takes about 90 days: 2 weeks to choose the use case and map compliance rules, 6 weeks to build and integrate, and 4 weeks to pilot on a small portfolio segment. A proof of concept can be ready in 3-4 weeks. Multi-region production rollouts take 4-6 months (Technource estimates).
They detect them and hand them off. Six common triggers stop the collection script, including a disputed debt, job loss or illness, a request for a person, and a mention of an attorney. The agent transfers the call with the transcript and account details. Disputes can trigger validation duties, so trained staff should own them.
A lending voice agent typically connects to six systems: the loan management system, loan origination system, CRM, payment gateway, telephony platform, and consent and do-not-call records. ICE built its 2026 servicing voice agent into its MSP platform to read loan data and pass context to human agents (ICE, March 2026).


 AI ConsultingStrategic AI Roadmaps