Learn how to build an app like Dave in 2026, from defining the right eligibility model and choosing a compliance path to building underwriting, repayment, and banking features. This guide covers the essential tech stack, development costs, regulatory challenges, and key lessons from Dave, MoneyLion, and Chime to help you build a scalable cash advance or earned wage access platform.
Key Takeaways
Dave dropped optional tips in late 2024. It now charges a mandatory $1–$5 monthly membership plus a 5% per-advance fee, capped at $15.
Dave and its CEO are named defendants in an active DOJ lawsuit over undisclosed fees. Copying the UI without copying the compliance work is the fastest way to repeat that mistake.
The CFPB’s December 2025 advisory opinion cleared “Covered EWA” of TILA credit rules, but state licensing laws still vary and are tightening.
A working MVP typically costs $20,000–$80,000. A full AI-underwritten platform runs $150,000–$350,000 or more.
The model works at scale: Dave posted $554.2 million in FY2025 revenue, up 60% year-over-year, largely on AI-driven underwriting that cut delinquency to a record low.
A $60 grocery bill lands three days before payday. Millions of Americans hit this exact wall every month.
A single overdraft can cost more than the shortfall itself, that gap is exactly what apps like Dave were built to close.
This guide breaks down how to build an app like Dave step by step: the build process, the tech stack, the real 2026 cost, and the regulatory risk most guides leave out.
The U.S. earned wage access market is projected to grow roughly 300% between 2024 and 2034 (CFPB, via HR Dive), so the timing for building in this space is real.
What Is Dave?
Dave is a US neobank that gives members interest-free cash advances up to $500 against their next paycheck, through a feature called ExtraCash, alongside a linked spending account, budgeting tools, and a side-hustle job finder.
It launched in 2017 with a narrow goal: help people avoid bank overdraft fees.
It has since grown into a full neobank, not just a cash-advance tool.
By the end of Q4 2025, Dave counted 14.1 million total members, up 17% year-over-year (Investing.com).
Dave’s 2026 Business Model
Dave earns money through a mandatory $1–$5 monthly membership plus a 5% service fee per ExtraCash advance, with a $5 floor and a $15 cap.
This replaced the old tip-based model after an FTC settlement over undisclosed fees eliminated optional tips in late 2024 (LendEDU, 2026).
Old Model (Pre-2024)
New Model (2026)
Optional “tips” on each advance
Mandatory 5% service fee ($5 floor, $15 cap)
$1/month membership
$1–$5/month membership, tiered by cohort
Express fee for instant delivery
Express fee still applies for instant delivery
Fee amount unclear before linking bank account
Fees disclosed upfront, post-FTC settlement
The shift worked financially, Dave’s net monetization rate hit a record 4.8% in 2025, and average revenue per ExtraCash origination rose 27% year-over-year (The Globe and Mail).
Competitors chose different models. MoneyLion offers up to $1,000 through a RoarMoney account with no subscription.
Klover skips subscriptions entirely and monetizes through data and in-app offers.
Chime’s MyPay charges a flat $2 for instant delivery instead of a percentage fee, and is scaled to a $400 million-plus annualized revenue run rate with a roughly 1% steady-state loss rate (Sacra).
How to Build an App Like Dave: Step-by-Step Guide
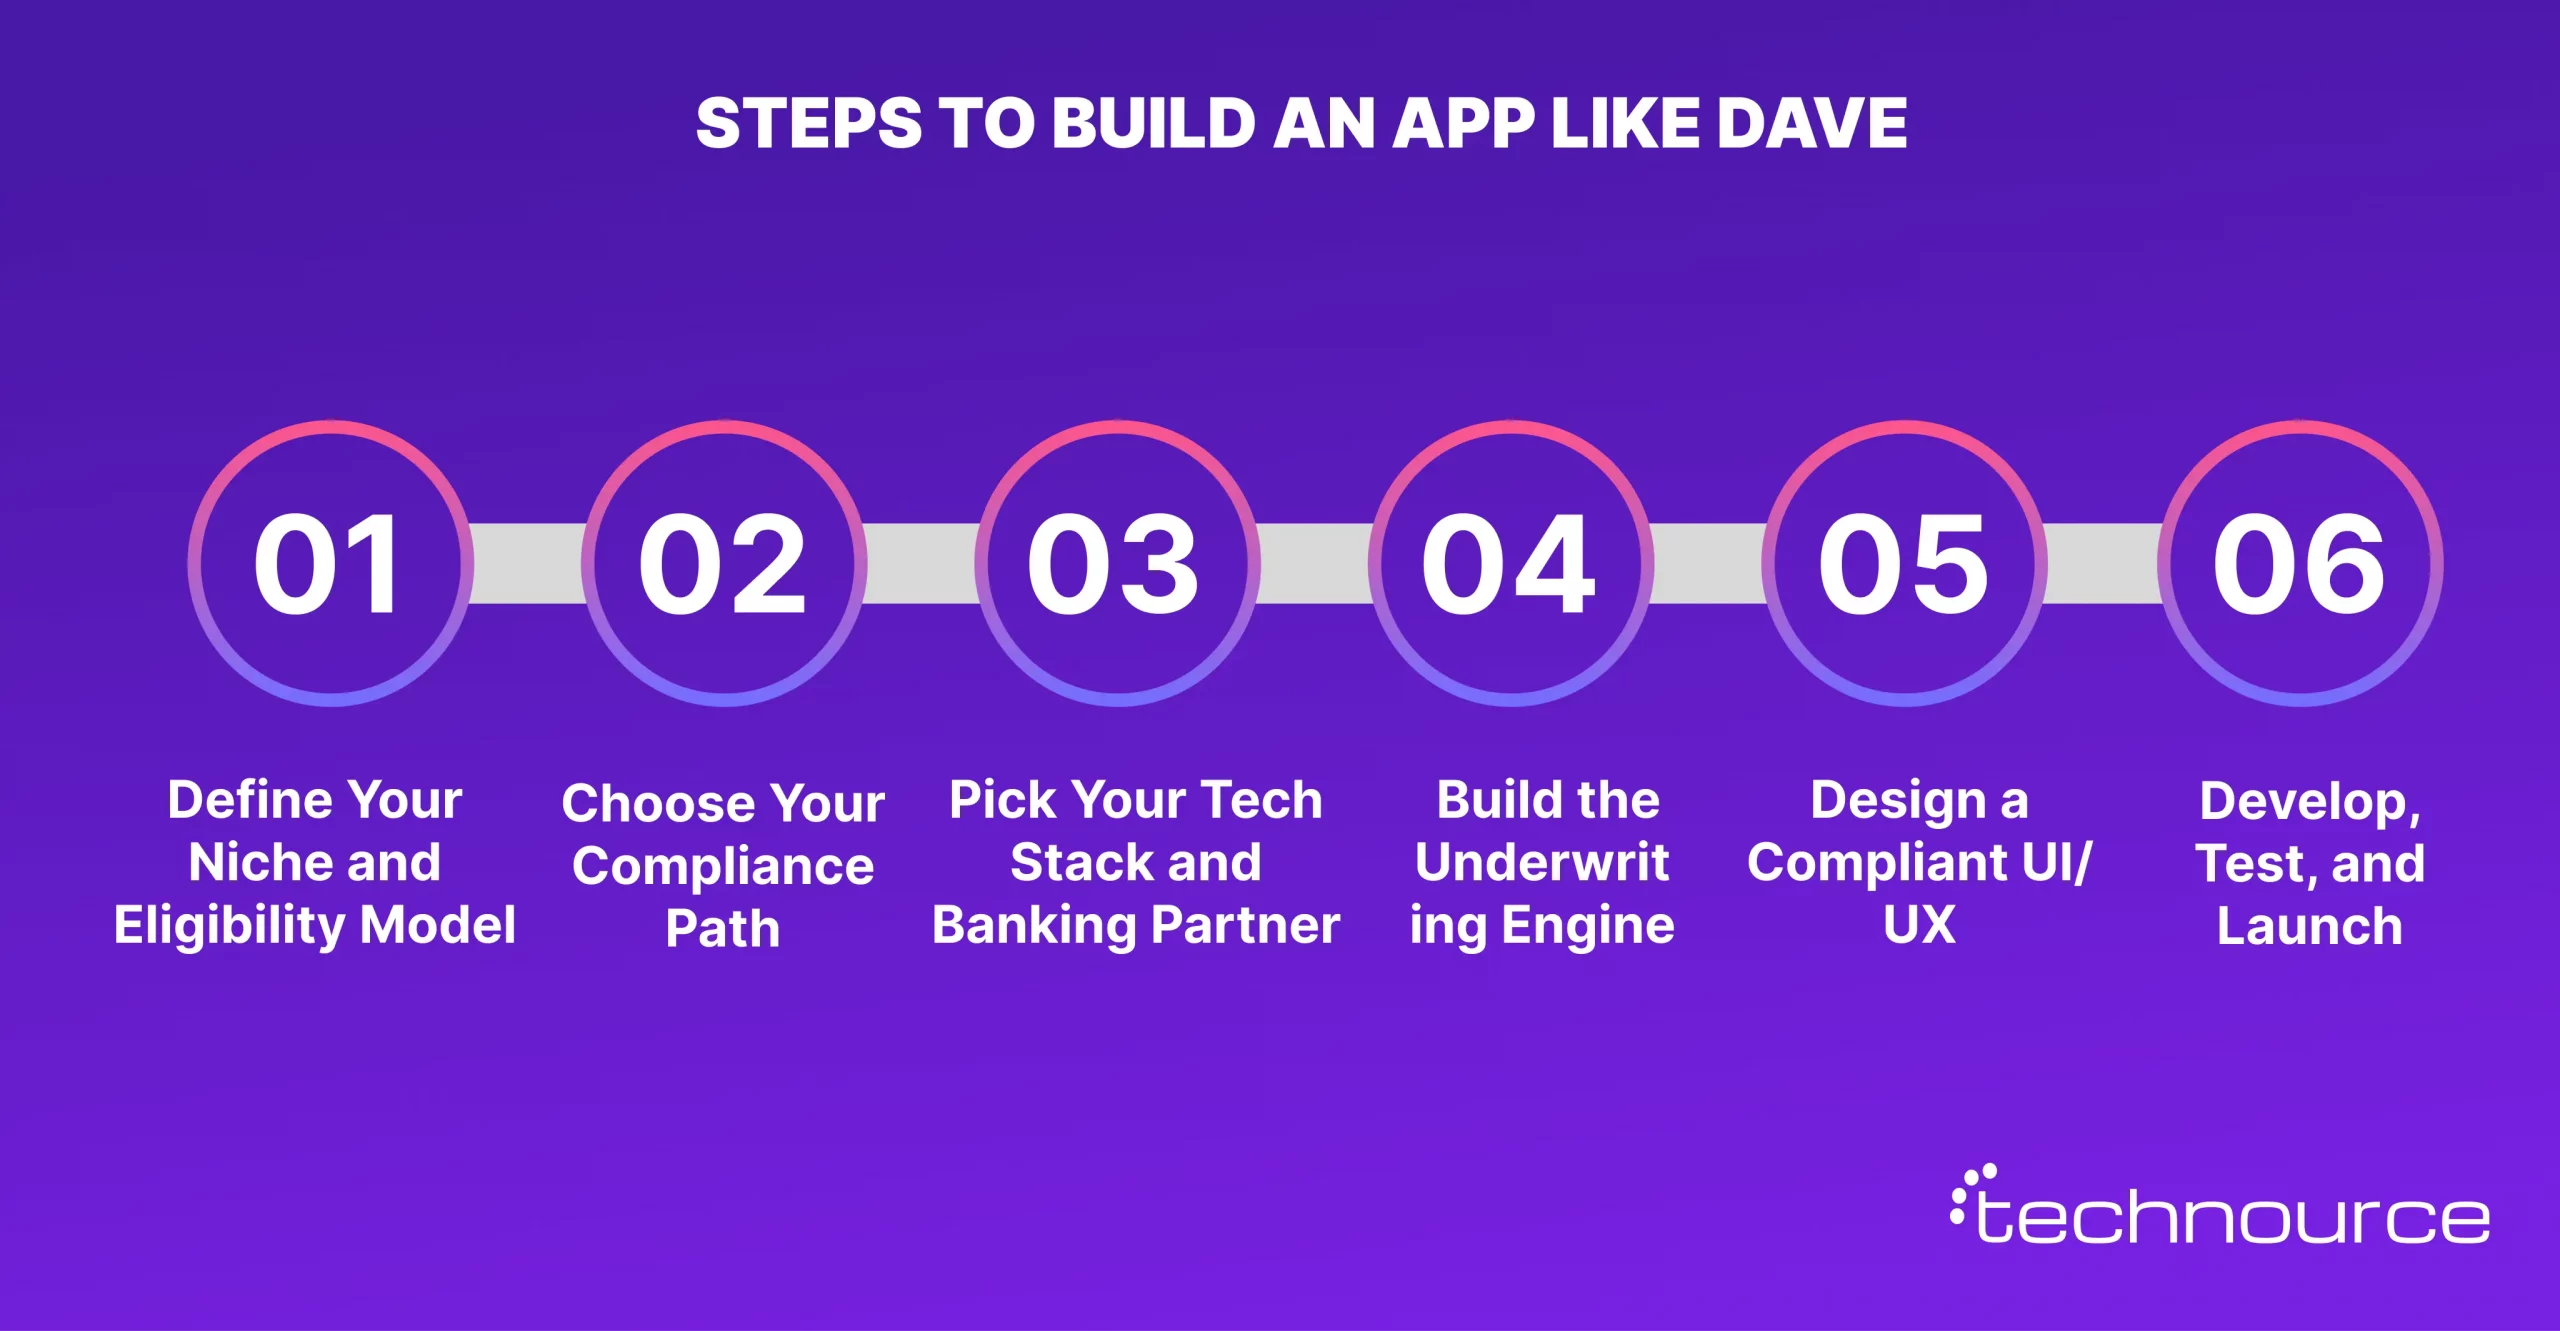
Building an app like Dave requires a structured approach that balances user experience with underwriting, banking infrastructure, and regulatory requirements. Each stage plays a role in creating a secure and scalable cash advance platform.
Step 1: Define Your Niche and Eligibility Model
Decide who you’re building for first: gig workers, hourly employees, or salaried staff.
Each group needs a different income-verification approach.
Gig workers lack a fixed paycheck, so you’ll need GPS or timesheet data instead of direct deposit history.
Salaried staff is easier to verify through recurring direct deposits.
What can go wrong: designing one eligibility model to fit everyone usually breaks the moment you try to scale into a second user segment.
Step 2: Choose Your Compliance Path
Decide early whether you’re building a “Covered EWA” model or a general lending product — this decision shapes your entire architecture.
Payroll-based EWA with no direct bank debit sits outside TILA under the CFPB’s December 2025 advisory opinion (Federal Register).
Bank-debit models like Dave’s still face state-by-state lending rules; California treats EWA transactions as loans, while Nevada and Missouri require licensing (Venable LLP).
Step 3: Pick Your Tech Stack and Banking Partner
Bank connectivity is the foundation. Most cash advance apps use Plaid or Yodlee for account linking and transaction history.
Back-end logic, underwriting, repayment scheduling, and ledgering typically run on Node.js, Python, or Java.
You’ll also need a sponsor bank, since fintechs like Dave don’t hold banking licenses directly; Dave’s own banking services run through Coastal Community Bank (The College Investor, 2026).
Step 4: Build the Underwriting Engine
This is the hardest technical piece of the app, harder than the UI, by far.
The engine scores eligibility using deposit history, spending patterns, and account tenure.
Dave’s own AI underwriting model cut 28-day delinquency to 1.89% in early 2026, a record low for the company (Simply Wall St).
What can go wrong: underpricing risk leads to losses; overpricing risk kills your approval rate and user growth before you have data to fix it.
Step 5: Design a Compliant UI/UX
Every fee must be disclosed before a user links their bank account, not after.
That’s exactly the disclosure gap the FTC accused Dave of exploiting in its original complaint (FTC.gov).
Show the total repayment amount upfront, service fee included, before the user commits to an advance.
What can go wrong: burying fees in fine print invites the same regulatory exposure Dave is now facing.
Step 6: Develop, Test, and Launch
Build in phases: eligibility engine first, then repayment automation, then supporting features like budgeting.
QA the repayment logic hardest; this is the part where real money actually moves.
Soft-launch with a small user cohort before opening broadly, so you can validate default rates with real (small-scale) data.
What can go wrong: skipping a soft launch means discovering underwriting flaws at full scale, with real money already deployed.
Core Features to Build
The right feature set should balance user convenience with responsible lending, repayment reliability, and long-term retention. These core capabilities form the foundation of a scalable cash advance app.
Instant Eligibility and Advance Engine
This is the feature users actually came for: a fast, accurate answer on how much they can borrow.
It pulls bank transaction history through Plaid or Yodlee, then scores income stability, spending patterns, and account tenure.
A weak scoring model shows up fast: either approval rates crash, or defaults climb.
Dave’s engine, for example, uses continuously retrained models rather than static rules, which is why its delinquency rate keeps falling even as advance volume grows.
Building this well takes real data science work, not a simple if-then rules engine bolted onto a mobile app.
Bank-Linked Automatic Repayment
Repayment has to happen automatically, on the user’s actual payday, without requiring any manual step.
Most apps use ACH debit against the linked checking account on the agreed settlement date.
If funds are short, the system needs a fallback: partial withdrawal, retry logic, or a linked debit card charge.
Get this wrong, and you create either failed collections or angry users hit with surprise overdrafts, the exact complaint that drew regulatory attention to Dave.
Clear, advance notice before any withdrawal attempt is now a baseline expectation, not a nice-to-have.
Spending or Checking Account
A linked spending account keeps users inside your app instead of routing cash elsewhere.
It needs a debit card, ATM access, and FDIC-insured pass-through banking via your sponsor bank.
This account is also where most apps capture interchange revenue, since every debit swipe generates a small fee from the merchant.
Building this from scratch is a significant compliance lift, which is why many fintechs partner with fintech software development alongside banking-as-a-service providers instead of building custody infrastructure themselves.
Skipping this feature is possible, but it caps your monetization to advance fees alone.
Side Hustle or Gig Marketplace
This feature connects users to short-term or gig work directly inside the app, useful for repayment and for user retention.
Dave’s version links to delivery, rideshare, and remote-work listings, functioning as both a user benefit and a referral revenue stream.
Technically, this is the easiest core feature to build, since it’s usually an API integration with third-party job boards rather than original infrastructure.
The real value is retention: users who find work through your app are less likely to churn.
Credit-Building Tools
Many users lack the deposit history to build traditional credit, so a credit-building feature like reporting on-time repayments adds real long-term value.
This typically means integrating with a credit bureau reporting partner, not building bureau infrastructure yourself.
It also strengthens the underwriting loop: repayment behavior you’re already tracking for advances doubles as a credit signal.
This feature differentiates a cash advance app from a payday loan in the eyes of both users and regulators.
Budgeting and Overdraft Alerts
Predictive budgeting, flagging an account before it goes negative, is what originally made Dave’s model work, before ExtraCash was even the main feature.
It requires transaction categorization and a forecasting model based on recurring bills and income timing.
Done well, this reduces the very overdrafts that justify the app’s existence, which builds trust rather than dependency.
Done poorly, it’s just a stale list of past transactions with no predictive value.
Real Benefits
Faster access to cash isn’t the real benefit; avoiding a costly overdraft cascade is.
A single missed payment can trigger a chain of declined transactions and repeat fees; interrupting that chain early is the actual business outcome.
Automated repayment isn’t just convenience; it’s what keeps default rates low enough for the underlying economics to work at scale.
Dave’s AI-driven underwriting is a direct example: cutting delinquency to 1.89% didn’t just reduce losses; it also pushed net monetization to a record 4.8% (The Globe and Mail) Better underwriting is a revenue lever, not just a risk-management one.
Real Examples: How Fintechs Are Winning With This Model
These fintechs show how different parts of the cash advance and EWA model can drive growth and profitability. Their approaches offer practical lessons for building a product with stronger underwriting, diversified revenue, and sustainable unit economics.
Dave Inc. – AI Underwriting as a Growth Lever
Dave’s proprietary underwriting model, CashAI, pushed 28-day delinquency down to a record 1.89% in early 2026, while full-year 2025 revenue grew 60% year-over-year to $554.2 million (The Globe and Mail).
The lesson: underwriting accuracy is a growth lever, not just a loss-prevention tool.
MoneyLion – Embedded Finance Turned a Loss Into Profit
MoneyLion grew FY2024 revenue 29% year-over-year to $546 million, and turned a $45.2 million net loss in 2023 into $9.1 million in net income (SEC filing) driven largely by its enterprise embedded-finance partnerships.
The lesson: a cash advance feature alone rarely reaches profitability; pairing it with an enterprise or marketplace revenue stream does.
Chime – Earned Wage Access as a Standalone Product Line
Chime scaled its MyPay earned wage access product to more than $400 million in annualized revenue with a roughly 1% steady-state loss rate after one year (Sacra) The lesson: a well-underwritten EWA product can become a major revenue line on its own, not just a retention feature.
Risks and Regulatory Challenges
This section is the one most competitor guides skip, and it’s the one that matters most if you’re actually building.
Dave Inc. and CEO Jason Wilk are named co-defendants in an active DOJ lawsuit (Case 2:24-cv-09566) alleging deceptive marketing, undisclosed fees, and non-consensual “tips” (FTC.gov, case status: pending).
This isn’t a settled, historical case; it’s ongoing, and it directly targets the exact business model this guide describes.
The regulatory picture is genuinely mixed: the CFPB’s December 2025 advisory opinion favors payroll-based “Covered EWA” models, but state legislatures keep adding new licensing requirements (FTC.gov, case status: pending).
This isn’t a settled, historical case; it’s ongoing, and it directly targets the exact business model this guide describes.
The regulatory picture is genuinely mixed: the CFPB’s December 2025 advisory opinion favors payroll-based “Covered EWA” models, but state legislatures keep adding new licensing requirements (PYMNTS).
The real cost to users can be steep if repayment windows are short; NerdWallet calculated an effective APR of roughly 260% on a $100 advance repaid in two weeks once fees are included (NerdWallet, 2026).
Building this product without a compliance-first approach isn’t just an ethical gap; it’s the specific gap regulators are actively litigating.
Tech Stack Required to Build an App Like Dave
The technology stack for a Dave-like app needs to support secure bank connectivity, real-time eligibility decisions, automated repayments, and scalable financial workflows. A typical architecture combines fintech APIs with cross-platform mobile app development, backend services, and machine learning for underwriting.
The cost of building an app like Dave depends on the features, level of automation, compliance requirements, and how much financial infrastructure you build versus integrate through third-party providers. The following estimates give a practical starting point for different build scopes.
Full platform (banking, budgeting, credit-building)
$150,000 – $350,000+
9–14 months
Compliance layer (KYC/AML, state licensing support)
+$10,000 – $25,000
Runs parallel to build
These figures track closely with current market benchmarks for comparable fintech builds.
Team location changes the math significantly; hourly rates can vary 4–8x between the highest- and lowest-cost development markets.
Future Trends
AI underwriting is becoming the primary competitive differentiator, not a back-end detail. Dave’s delinquency improvements are a direct result of continuous model retraining (Simply Wall St).
Regulatory clarity is pulling more entrants into the payroll-based EWA model specifically, since it now sits outside TILA under the CFPB’s December 2025 opinion (Goodwin Law).
Employer-embedded EWA is growing as its own category, separate from consumer-facing apps, as the overall EWA market is projected to expand roughly 300% by 2034 (HR Dive).
Why Technource
Technource brings fintech product engineering experience across digital lending, payments, banking, and crypto platforms, with capabilities spanning underwriting logic, KYC/AML integrations, secure transaction workflows, and financial API integrations.
Its approach combines product engineering with compliance and security considerations from the discovery stage, helping teams choose the right balance of custom software development and third-party financial infrastructure.
For a Dave-like cash advance or EWA platform, this means building the eligibility, repayment, and financial workflows around the product’s regulatory and scalability requirements rather than treating compliance as a later-stage add-on. Here are some ticks that we fill in your checklist:
Fintech-specific engineering depth, underwriting logic, sponsor-bank integration, and KYC/AML are core competencies, not add-ons.
Experience navigating the current EWA compliance landscape, including state-by-state licensing differences.
A build-vs-buy approach to banking infrastructure that avoids the common mistake of over-building custody systems in-house.
Conclusion
Building an app like Dave means building a compliance-first underwriting product, not just a mobile UI on top of a bank feed.
Effective fintech app development services must account for a defensible eligibility model, transparent fee disclosure, and a compliance path that matches your repayment mechanism.
Next step: map your eligibility model and compliance path before writing a single line of front-end code.
FAQs
Dave charges a mandatory $1–$5 monthly membership plus a 5% service fee per cash advance, capped at $15. It dropped optional tips in late 2024.
An MVP takes 3–5 months. A full-featured platform with banking, budgeting, and credit-building tools typically takes 9–14 months.
Earned wage access (EWA) lets users draw wages they’ve already earned before payday, usually through payroll data. Cash advance apps like Dave estimate eligibility from bank transaction history instead.
Yes, but compliance requirements vary by state and by model. Payroll-based EWA is treated differently from bank-debit models like Dave’s under current CFPB guidance.
Public reporting doesn’t confirm Dave’s exact stack, but comparable apps use Plaid or Yodlee for bank connectivity, Node.js or Python for back-end logic, and React Native or Flutter for the mobile app.
Most apps score eligibility using bank transaction history, deposit consistency, spending patterns, and account tenure, pulled through a service like Plaid rather than a traditional credit check.