This guide explores the best fintech apps of 2026, the major fintech app categories, must-have features, technology stacks, development costs, and key industry trends. It also covers the step-by-step development process, build-vs-buy considerations, and how to choose the right fintech development partner. Whether you’re planning a fintech MVP or a full-scale financial platform, the guide helps you understand the technology, compliance, costs, and strategic decisions involved in building one that can scale.
Key Takeaways
The global fintech market is valued at $395–460 billion in 2026 and growing at 16–25% CAGR.
Revolut hit $6 billion in 2025 revenue. Chime went public in 2026 at a ~$11 billion valuation.
Fintech app development costs range from $20K for a basic MVP to $300K+ for an enterprise platform.
Compliance overhead, not feature count, is what actually drives fintech app cost up.
AI-driven fraud detection and embedded finance are the two biggest fintech app differentiators in 2026.
Half the “best fintech apps” lists online still recommend Mint. Mint shut down in 2024.
That’s the risk of building a product plan on outdated references.
Picking the wrong benchmark app or the wrong cost estimate early can misdirect months of scoping and budget.
This guide covers the fintech apps that will actually lead in 2026, the features users now expect, real development costs, and how to choose a build partner.
A fintech app is a mobile or web application that delivers financial services digitally- banking, payments, lending, investing, or insurance- without a physical branch.
What separates a 2026 fintech app from an older banking app is what runs underneath it.
Modern fintech apps layer AI-driven decisioning, embedded finance APIs, and compliance controls from day one.
Older apps bolted these on after launch, which is exactly why so many legacy platforms are now being rebuilt instead of patched.
Best Fintech Apps of 2026
These are the apps actually leading their categories in 2026, updated from outdated lists still citing discontinued products.
App
Category
2026 Signal
What It Means for Builders
Revolut
Neobank / Super-app
$6B revenue, $2.3B pre-tax profit, 11 product lines each over $135M
Diversified revenue beats single-product apps at scale
Chime
Neobank
IPO’d 2026 at ~$11B valuation, 22M+ US users
Lending (MyPay) is what got Chime to profitability
Nubank
Neobank
110M+ users, dominant across Latin America
Credit-led growth works best in underbanked markets
Robinhood
Investment / Trading
Pioneered commission-free trading at scale
Zero-fee models need volume – plan monetization elsewhere
Coinbase
Crypto / Investment
Major on-/off-ramp for crypto in the US
Custody and compliance cost more than the trading UI
Cash App
Payments / Wallet
Leading US P2P payment share alongside Venmo
P2P trust is built through speed, not features
PayPal
Payments / Wallet
Still the default for online checkout and B2C payments
Merchant trust and network effects are hard to disrupt
1. Revolut
Revolut started as a multi-currency travel card in 2015 and has since expanded into a genuine financial super-app, banking, stock and crypto trading, insurance, and business accounts all live in one product.
It runs 11 separate product lines, each generating over $135 million a year, rather than depending on one core banking feature.
That spread pushed it to $6 billion in 2025 revenue and $2.3 billion in pre-tax profit, with card payments alone contributing $1.3 billion (+45% YoY) and subscriptions $936 million (+67% YoY).
For builders, the lesson is architectural as much as strategic: Revolut’s product lines share a single ledger and compliance core, which is what let it launch new verticals fast without rebuilding trust and KYC each time.
2. Chime
Chime built its US base by partnering with FDIC-insured banks instead of chasing its own banking charter, which let it launch faster and cheaper than a licensed neobank.
It went public in 2026 at roughly an $11 billion valuation, a real haircut from its 2021 peak of $25 billion, but this time backed by actual adjusted profitability.
Its MyPay earned-wage-access product and SpotMe fee-free overdraft feature gave it a second revenue line beyond interchange, which is what got it there.
Chime’s core lesson for builders: a single well-executed lending or credit feature can outweigh a long list of minor ones.
3. Nubank
Nubank has crossed 110 million users, making it the largest neobank in the world by user count and the largest digital bank outside Asia.
It was built credit-first from day one; its original 2014 product was a no-fee, fully app-controlled credit card, at a time when Brazilian banks charged heavily for basic accounts.
That credit focus has scaled into a broader lending portfolio, with roughly 29 million customers getting their first-ever credit card through Nubank and full 2025 revenue reaching $16.3 billion.
Its model works specifically because it targets underbanked markets, Brazil, Mexico, and Colombia, where traditional banks left a real gap rather than a crowded, saturated one.
4. Robinhood
Robinhood pioneered commission-free stock trading and forced the entire brokerage industry to drop trading fees within a few years of its launch.
It generated $4.5 billion in 2025 revenue, up 52% year-over-year, the fastest growth rate among publicly traded US brokerages that year.
Its Gold subscription line hit a record 4.2 million subscribers, and its newer prediction-markets product briefly out-earned its crypto segment, generating $156 million from 13.6 billion contracts traded.
For builders, Robinhood shows that a zero-fee core product still needs a second monetization layer; subscriptions and net interest income now carry as much weight as trading volume.
5. Coinbase
Coinbase is the main on- and off-ramp for crypto in the US, holding over 50% of the domestic spot market and roughly 7% of global exchange volume.
It reported $7.2 billion in 2025 revenue and 120 million verified users, though only about 8.7 million are monthly transacting users, a gap worth noting for anyone assuming registered users equal active ones.
Subscriptions and services now make up roughly 40% of total revenue, up from about 4% in 2020, largely thanks to Coinbase One and its Base Layer-2 network.
The takeaway for builders: a crypto-native app needs a non-trading revenue line just as much as a traditional fintech app does, since trading volume swings hard with market cycles.
6. Cash App
Cash App started as a simple peer-to-peer payment tool from Block (formerly Square) and has since layered in banking, investing, and Bitcoin trading on top.
It holds a leading share of the US P2P payments market alongside Venmo, built more on transfer speed than a long feature list.
It generated $7.2 billion in 2025 revenue, an 18% increase, with roughly 59 million monthly active users and $9.6 billion of that revenue coming from Bitcoin transactions alone.
Cash App’s Bitcoin dependency is also a caution for builders — a revenue line tied that closely to one volatile asset class can swing hard when crypto markets cool.
7. PayPal
PayPal remains the default checkout option for online merchants across the US and Europe, more than 25 years after launch.
It closed 2025 with 439 million active accounts and $33.2 billion in revenue, processing $1.79 trillion in total payment volume across roughly 25 billion transactions.
Venmo and buy-now-pay-later products have become real growth drivers rather than side features, helping offset the slower growth in PayPal’s core checkout business.
PayPal’s staying power comes from network effects, not novelty; merchants keep it because customers expect it, and that two-sided lock-in is hard for any new entrant to replicate.
Types of Fintech Apps
Fintech apps fall into seven broad categories, and most products combine two or more depending on their target users and business model.
Category
Typical Dev Complexity
Cost Tier
Digital Banking / Neobank
High – banking license or BaaS partnership required
These replace a traditional bank account with a fully mobile experience, checking, savings, cards, and transfers.
Revolut and Chime are the clearest examples, and both now run multiple product lines beyond basic banking to stay profitable.
Building in this category means budgeting for banking-as-a-service partnerships or a direct banking license, plus FDIC/FCA-equivalent compliance from day one.
2. Payments & Digital Wallets
These apps move money between people or businesses, peer-to-peer transfers, QR payments, or merchant checkout.
PayPal and Cash App dominate this category because they solve trust and speed simultaneously.
The core technical challenge is real-time settlement without sacrificing fraud controls, which is where most payment app timelines slip.
3. Investment & Trading Apps
These let users buy, hold, and trade stocks, ETFs, or crypto directly from a phone.
Robinhood proved commission-free trading works at scale; Coinbase proved the same for crypto.
Regulatory licensing (SEC, FINRA, or regional equivalents) is the long pole here, often taking longer than the engineering build itself.
4. Lending Apps
These handle loan origination, underwriting, and repayment; personal loans, BNPL, or payday-style advances.
Chime’s MyPay and Nubank’s credit products show lending is now a primary revenue engine for neobanks, not a side feature.
Underwriting logic and credit risk models are the hardest part to get right, and the most expensive to get wrong.
5. Insurance Apps (Insurtech)
These apps handle policy management, claims, and premium payments digitally.
Automated reminders and instant claims processing are now baseline user expectations, not differentiators.
Insurtech builds carry heavier compliance loads than most other fintech categories because of state-by-state insurance regulation in the US.
6. Personal Finance Management Apps
These apps track spending, set budgets, and surface savings insights across linked accounts.
Post-Mint, this category has a real gap; no single app has taken over as the default budgeting tool.
AI-driven spend categorization and predictive insights are now the expected baseline, not a premium feature.
7. Embedded Finance / Banking-as-a-Service
This is the newest category: non-financial companies embedding payments, lending, or banking directly into their own product.
Stripe’s platform push and the broader BaaS trend are why e-commerce and SaaS companies now offer built-in financing without becoming a bank themselves.
This is also the fastest-growing build category Technource is seeing in client conversations for 2026.
Technology Stack Behind Modern Fintech Apps
The technology stack matters because fintech applications handle sensitive financial data and transactions where downtime, security gaps, or data integrity issues can directly impact users and revenue.
Layer
Common Choices
Why It’s Used
Backend
Node.js, Java (Spring Boot), Go
Handles high-concurrency transactions reliably
Database
PostgreSQL, MongoDB
PostgreSQL for ledger accuracy; MongoDB for flexible user data
Cloud & DevOps
AWS, Azure, Kubernetes
Auto-scaling during payment spikes, region-specific data residency
Security
OAuth 2.0, AES-256 encryption, tokenization
Meets PCI DSS requirements for handling card data
AI/ML
Python, TensorFlow, AWS Fraud Detector
Powers real-time fraud scoring and credit models
None of these choices are exotic; the differentiator is how carefully they’re configured for compliance, not which vendor is picked.
Must-Have Features in a High-Performing Fintech App
AI-Powered Fraud Detection
Real-time transaction scoring is now table stakes, not a premium add-on.
Apps without it see higher chargeback rates and slower user trust; fraud detection pays for itself within the first year for most lending and payments apps.
Real-Time Notifications
Users expect instant alerts for every transaction, login, and balance change.
This isn’t just UX polish; it’s also a core fraud-prevention layer, since users catch unauthorized activity faster than backend systems often do.
Biometric & Multi-Factor Security
Face ID, fingerprint, and device-based MFA are now the minimum bar for any app touching money.
Apps that still rely on SMS-only 2FA are increasingly flagged as weak by both users and auditors.
Building this in from day one avoids the expensive retrofit most startups face after their first compliance audit.
Embedded Finance / API Layer
Even single-purpose apps now need APIs for card issuing, ledger management, or payment rails.
Building on existing BaaS infrastructure instead of from scratch is usually the faster and cheaper path here.
Budgeting & Spend Analytics
Category-level spend tracking and savings goals are now expected in almost every consumer fintech app, not just dedicated budgeting tools.
AI-driven categorization has replaced manual tagging as the default.
Real Benefits: Tied to Business Outcomes
A high-performing fintech app needs to do more than move money or display financial data. Users expect fast transactions, strong security, transparent communication, and intelligent financial insights, while businesses need the infrastructure to manage fraud, compliance, and growing transaction volumes.
The right feature set depends on the type of fintech product, but these capabilities have become increasingly important across banking, payments, lending, and personal finance apps.
Feature
Business Outcome
AI fraud detection
Reduces chargeback losses and lowers manual review costs per transaction
Instant KYC onboarding
Cuts signup drop-off; slow onboarding is the #1 reason fintech apps lose users pre-activation
Embedded lending (e.g., Chime’s MyPay)
Adds a second revenue line, a key reason profitable neobanks pulled ahead of unprofitable ones
Custom UI/UX vs. templated design
Can lift onboarding completion by 30–35%, directly improving retention
Risks & Challenges in Fintech App Development
Fintech carries risks most consumer apps never face — this is the section that separates a serious build plan from a rushed one.
Missing one regulatory requirement can delay launch by months or trigger fines post-launch
Legacy bank/core-system integration
Banking partner APIs are often slower and less documented than expected, extending timelines
Fraud & security exposure
A single breach can end user trust permanently; fintech has near-zero tolerance for security failure
Profitability pressure
Over 76% of neobanks remain unprofitable in 2026; most fail on unit economics, not product
Underwriting/credit risk (lending apps)
Bad risk models create losses that compound quietly until a portfolio review exposes them
How to Build a Fintech App: Step-by-Step Process
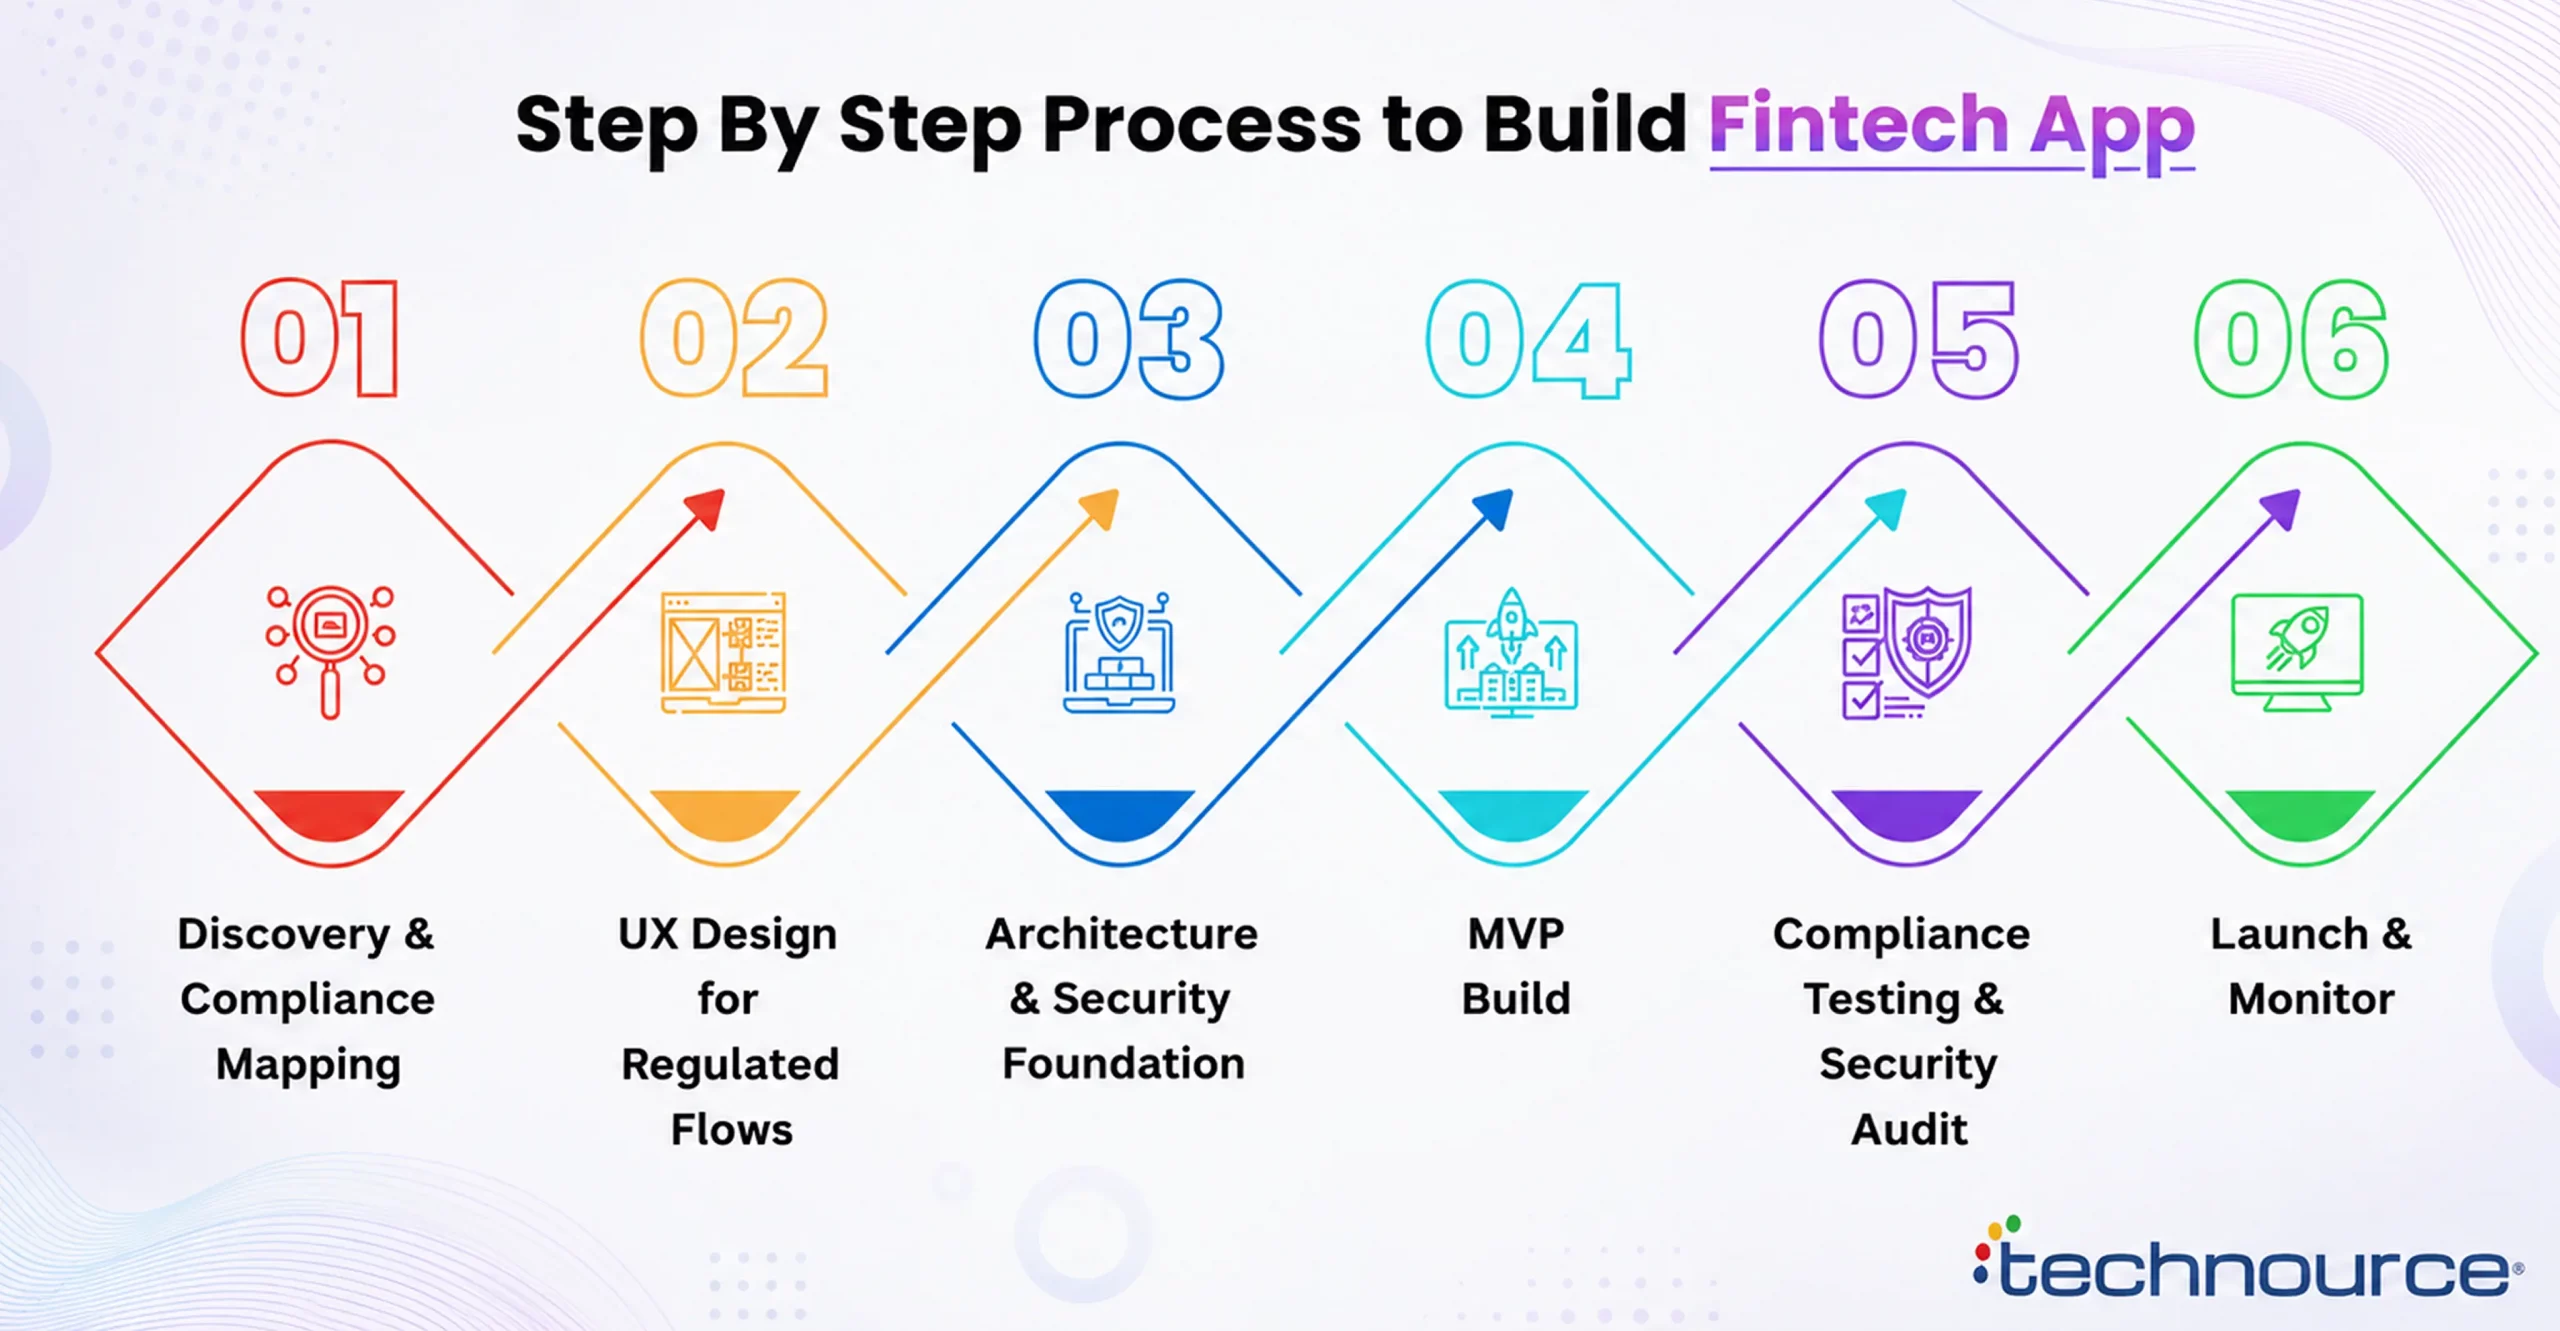
Building a fintech app requires more than designing screens and integrating payment APIs. Compliance, security, financial integrations, and transaction reliability must be considered from the start to avoid costly rework and prepare the product for a secure, compliant launch.
Step 1: Discovery & Compliance Mapping
Before any design work starts, map which regulations apply: PCI DSS for card data, PSD2 for EU payments, KYC/AML for onboarding, and any state or regional licensing.
Skipping this step is the single most common reason fintechs blow their budget, because compliance requirements discovered mid-build force expensive rework.
Step 2: UX Design for Regulated Flows
Onboarding, KYC, and payment confirmation screens need to feel simple while still capturing everything compliance requires.
Teams that treat compliance screens as an afterthought end up with clunky flows that tank activation rates.
Step 3: Architecture & Security Foundation
This includes encryption standards, secure API design, and a ledger architecture that can pass an audit.
Retrofitting security after launch typically costs more than building it correctly from the start.
Step 4: MVP Build
Build an MVP with the smallest version that proves the core financial workflow end-to-end, one user type, one core transaction path.
Resist the urge to add every feature at once; a focused MVP is what actually gets funded and validated fastest.
Step 5: Compliance Testing & Security Audit
Third-party penetration testing and compliance audits should happen before launch, not after a regulator asks for them.
Budget both time and cost for this stage explicitly; it’s often underestimated in early planning.
Step 6: Launch & Monitor
Post-launch, fraud patterns and compliance requirements keep evolving, so monitoring isn’t a one-time task.
Plan for ongoing regulatory updates as a permanent line item, not a one-off cost.
Fintech App Development Cost in 2026
Cost is driven mainly by compliance and integration overhead, not just the feature list.
Tier
Cost Range
What’s Included
Basic MVP
$20,000 – $50,000
Single platform, core auth, basic transactions, minimal compliance scope
AI fraud detection, multi-jurisdiction compliance, advanced integrations, admin dashboards
AI features like fraud detection or credit scoring typically add 20–40% to the total build cost, across all tiers.
Build vs. Buy: Platform vs. Custom Development
Not every fintech idea needs a fully custom build.
White-label or BaaS platforms make sense for straightforward wallet or card products where speed to market matters more than differentiation.
Custom software development makes sense when the underwriting logic, compliance workflow, or user experience is the actual product differentiator; trying to force that onto a templated platform usually backfires within the first year.
Future Trends in Fintech App Development
Fintech is moving toward smarter risk management, embedded financial services, and more diversified revenue models.
As these shifts become mainstream, fintech companies need to plan their product architecture and monetization strategies around capabilities that can scale with changing user expectations and financial infrastructure.
AI-Driven Fraud & Credit Scoring
AI is moving from a nice-to-have to the default underwriting and fraud layer across nearly every fintech category.
Embedded Finance Expansion
More non-financial platforms are embedding payments and lending directly, following the BaaS model Stripe and others have scaled.
Stablecoin Infrastructure
Traditional payment networks are moving into stablecoin rails; Mastercard agreed to acquire stablecoin infrastructure firm BVNK for up to $1.8 billion in March 2026 (Expert Market Research).
This signals stablecoin settlement is moving from experimental to mainstream infrastructure over the next two years.
Second Revenue Lines as the Default, Not the Exception
Every profitable neobank examined in this guide- Revolut, Nubank, Chime- got there through a second product line, not through scaling the original one harder.
Teams scoping a new fintech app in 2026 should plan a second monetization path from the start, instead of treating it as a year-two roadmap item.
How to Choose the Right Fintech App Development Company
The right partner matters more in fintech than in almost any other app category, because mistakes here carry regulatory and financial risk.
Checklist Item
Why It Matters
Prior fintech-specific project experience
Generalist dev shops often miss compliance requirements until late in the build
Named compliance/security expertise
PCI DSS and KYC/AML aren’t things to learn on your project
Transparent, tiered cost estimates
Vague pricing usually means scope creep is coming
Post-launch support model
Fraud patterns and regulations change; you need a partner who stays engaged
Why Technource
Technource brings hands-on fintech engineering experience across digital lending, payments, banking, and crypto platforms, with projects such as Cashguru, a Singapore-based digital loan marketplace, and SuitMe, a crypto trading and staking platform.
Its fintech teams work across KYC integrations, secure transaction workflows, third-party financial APIs, and scalable product architecture, while following a security-first development approach.
This combination of domain experience and product engineering helps teams move from fintech MVPs to production-ready platforms without treating compliance, security, or scalability as post-launch concerns.
Technource approaches fintech builds with compliance mapped in from the discovery phase, not bolted on after a security audit flags gaps.
For teams evaluating build vs. buy, Technource’s SaaS product engineering team scopes both paths honestly before recommending one.
Conclusion
The fintech apps winning in 2026 share one trait: a second revenue line beyond their core product, whether that’s lending, subscriptions, or embedded finance.
Development cost for fintech software development services is driven by compliance and integration work, not just features; budget accordingly from day one.
If you’re scoping a fintech build, start with a compliance map before a feature list; it changes both the cost and the timeline.
FAQs
There isn’t one single best app — Revolut leads on revenue diversification, Nubank leads on user count, and Chime leads on the 2026 US neobank IPO story.
Fintech app development costs range from $20,000 for a basic MVP to $300,000+ for an enterprise-grade platform, depending on compliance scope and features.
AI-powered fraud detection is the single most important feature — it directly affects user trust, chargeback losses, and regulatory standing.
Buy (white-label/BaaS) for standard wallet or card products; build custom when your underwriting logic or UX is the actual differentiator.
A basic MVP typically takes 3–6 months; a full-featured compliant app takes 6–12 months, and enterprise platforms can take 12–18+ months.
Intuit discontinued Mint in 2024 and migrated users to Credit Karma, ending what was once the most recommended personal finance app in the category.
Most fintech apps need PCI DSS for card data, KYC/AML for onboarding, and either PSD2 (EU) or equivalent local payment regulations depending on the target market.